Complete Investor Guide to UAE Property

Tax-free property investment in Dubai, Abu Dhabi, and the wider Emirates

Updated February 14, 2026Beginner25 min read

Rental yield
6.7%
Gross, indicative
Price growth
9.0%
Year on year ยท Sep 2026
Transfer tax
4.0%
Currency
AED

Key takeaways

  • Freehold ownership is only available in designated zones -- verify the area before purchasing
  • The 4% DLD registration fee is a significant upfront cost; budget for it alongside agent commission (typically 2%)
  • Service charges vary enormously by building and area (AED 10-60+ per sq ft annually) -- always verify before purchase

Market Overview

The UAE economy continues to deliver robust growth driven by successful diversification away from oil dependency. The Dubai 2040 Urban Master Plan, ADGM expansion, tourism targets of 25 million annual visitors, and the Emirates' positioning as a global AI and technology hub all underpin strong property demand. Population growth through skilled migration and the Golden Visa program are key demand drivers for real estate.

Country
United Arab Emirates
Currency
AED (pegged to USD at 3.6725)
Population
10.3 million (approximately 88% expatriate)
GDP growth
3.4% (typically 3-5% range)
Inflation
2.1% (typically 1.5-3.0%)

Key industries

  • Oil & Gas
  • Tourism & Hospitality
  • Financial Services (DIFC/ADGM)
  • Technology & AI
  • Real Estate & Construction
  • Logistics & Trade

Restrictions

Freehold vs Leasehold Zones

Restrictive

Foreign nationals can purchase freehold property in government-designated freehold zones. Outside these zones, foreigners may acquire leasehold interests (typically 99 years) or usufruct rights. The distinction is critical and determines your ownership structure.

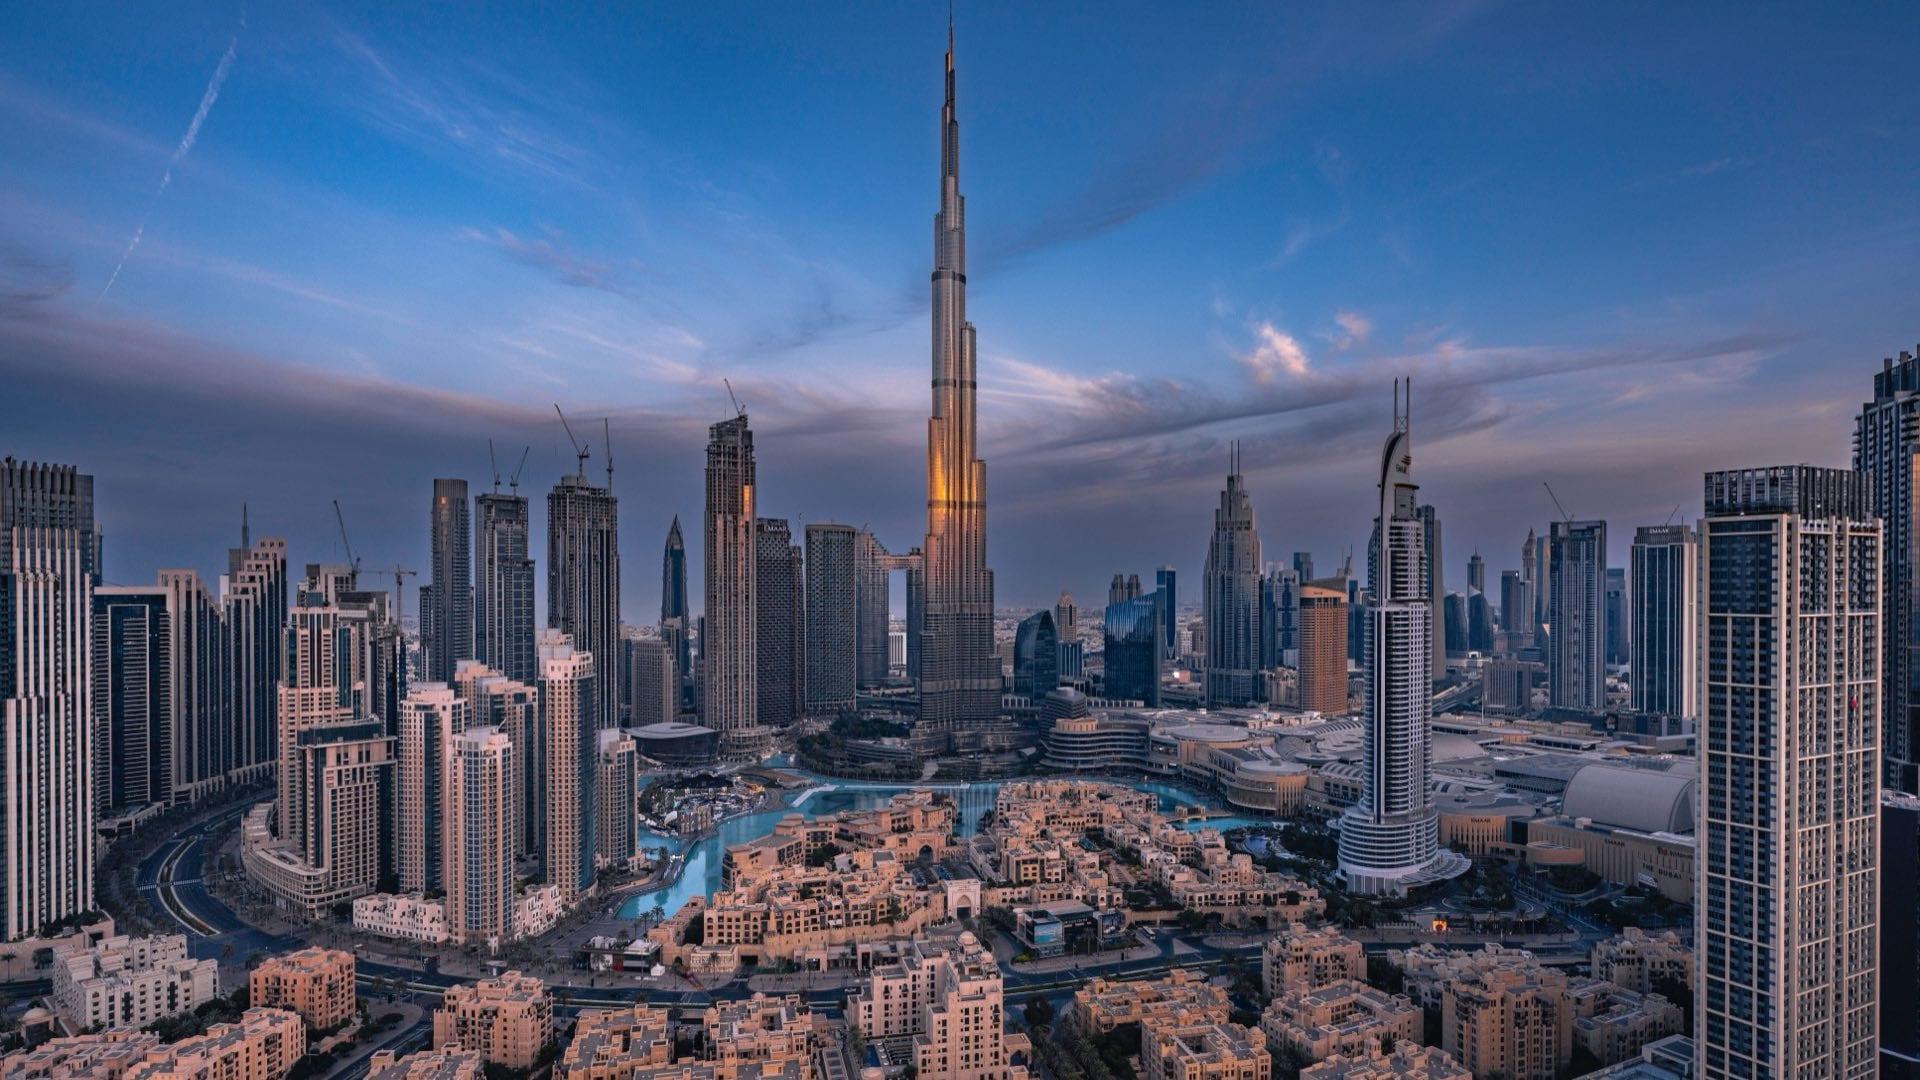
  • Freehold zones in Dubai: Dubai Marina, Downtown Dubai, Palm Jumeirah, JVC (Jumeirah Village Circle), Business Bay, JLT (Jumeirah Lakes Towers), DIFC, Dubai Hills, Arabian Ranches, Dubai Sports City, and many more
  • Freehold zones in Abu Dhabi: Saadiyat Island, Yas Island, Al Reem Island, Al Maryah Island, Masdar City
  • Leasehold areas: 99-year lease agreements available in non-freehold zones
  • Sharjah: More limited foreign ownership; Tilal City and Aljada are key freehold-eligible projects
  • All Emirates: Freehold ownership grants full title deed registered with the land department
No Nationality Restrictions in Freehold Zones

Open

Within designated freehold zones, foreign buyers face no nationality restrictions, approval requirements, or ownership limits. The UAE actively encourages foreign property investment as part of its economic diversification strategy.

  • No government approval required for foreign buyers in freehold areas
  • No residency requirement to purchase (can buy as a non-resident visitor)
  • No restrictions on number of properties owned
  • Equal ownership rights as UAE nationals within freehold zones
  • Corporate entities can also purchase freehold property in designated areas

Taxes & Fees

Property Registration Fee (DLD Transfer Fee)

4% of property value (Dubai); 2% (Abu Dhabi)

The primary transaction cost in UAE property purchases. Paid to the Dubai Land Department (DLD) upon registration of the property transfer. This is a one-time fee, not an annual tax.

Additional information

  • 4% of the property sale price, paid to Dubai Land Department at transfer
  • Traditionally split 50/50 between buyer and seller, though this is negotiable
  • Additional AED 580 DLD admin fee and AED 4,200 title deed issuance fee
  • Abu Dhabi charges 2% registration fee (lower than Dubai)
  • Mortgage registration fee: 0.25% of the loan amount + AED 290 admin fee

Exemptions

  • No exemptions for foreign buyers -- flat rate applies to all transactions

Rental Income Tax

0% (No personal income tax)

The UAE imposes zero personal income tax, including on rental income from property. This is one of the UAE's most significant advantages for property investors. However, investors should be aware of their tax obligations in their country of tax residence, which may tax worldwide income.

Additional information

  • No personal income tax applies in the UAE
  • No withholding tax on rental payments
  • Rental income is retained in full by the property owner
  • Note: Corporate Tax (9%) introduced in 2023 applies to business income, but individual property rental income from personal ownership is generally exempt
  • Investors should check their home country tax obligations on worldwide income

Exemptions

  • All individual rental income is tax-free in the UAE

Capital Gains Tax

0% (No capital gains tax for individuals)

The UAE has no capital gains tax for individual property investors. Profits from property sales are not taxed at the federal or emirate level. This makes the UAE particularly attractive for investors seeking capital appreciation strategies.

Additional information

  • No capital gains tax on property sales for individuals
  • No distinction between short-term and long-term holdings
  • Full sale proceeds (after transaction costs) retained by the seller
  • Corporate Tax (9%) may apply if property is held by a business entity above the threshold
  • Home country capital gains obligations may still apply -- consult your tax advisor

Exemptions

  • All individual capital gains from property are tax-free

Annual Property Tax

0% (No annual property tax)

The UAE does not levy annual property taxes. There is no equivalent of council tax, rates, or annual property tax found in most Western countries. However, a housing fee (5% of annual rental value in Dubai) is charged through utility bills, and service charges apply to all properties.

Additional information

  • No annual property tax or council tax equivalent in any emirate
  • Dubai Housing Fee: 5% of annual rental value (DEWA utility bill surcharge, paid by tenants)
  • Abu Dhabi Municipality Fee: similar structure applied via utility bills
  • Service charges (maintenance fees) are NOT a tax but a mandatory building maintenance contribution
  • Service charges in Dubai typically range AED 10-60 per sq ft per year depending on the community

Exemptions

  • No annual property tax exists -- this is structural, not an exemption

Value Added Tax (VAT)

5% on commercial properties; 0% on residential

VAT at 5% was introduced in the UAE in 2018. It applies to commercial properties but residential properties benefit from favorable treatment. Understanding the distinction is important for investors considering commercial real estate.

Additional information

  • 5% VAT applies to commercial property sales and rentals
  • Residential property sales and rentals are VAT-exempt (zero-rated for first sale of new residential within 3 years)
  • First sale of new residential property by developer is zero-rated (not exempt)
  • Subsequent residential sales are exempt from VAT
  • Service charges may include VAT on certain management components

Exemptions

  • Residential property sales (first sale zero-rated, subsequent exempt)
  • Residential rentals (exempt from VAT)

Requirements

Physical Visit

Optional

Not legally required -- many international buyers purchase remotely, especially off-plan properties. However, visiting is strongly recommended for resale purchases to inspect the property and understand the neighborhood.

Process

  1. Engage a RERA-licensed agent before visiting
  2. Schedule property viewings and area tours
  3. Visit during different times of day to assess noise, traffic, and community activity
  4. Meet with legal and financial advisors in person if possible

Alternatives

  • Virtual property tours and 3D walkthroughs
  • Local agent representation with video calls
  • Power of Attorney for remote purchase completion

Company Incorporation

Optional

Not required for property purchase. Individual foreign buyers can own freehold property directly in designated areas. Company structures may be considered for asset protection or multi-investor arrangements, but add complexity and cost.

Process

  1. Most individual buyers purchase in personal name (simplest and most common)
  2. If forming a company: consider free zone entities (e.g., JAFZA, DMCC)
  3. Obtain trade license if incorporating
  4. Open corporate bank account

Alternatives

  • Direct personal ownership (most common for individuals)
  • Trust structures
  • Offshore company ownership

UAE Bank Account

Required

Required for mortgage financing and strongly recommended for all transactions. UAE bank accounts are needed for utility payments, service charges, and rental income collection. Major banks serving foreign buyers include ADCB, Emirates NBD, Mashreq, and FAB.

Process

  1. Provide valid passport and UAE entry stamp
  2. Proof of income (salary certificate or bank statements)
  3. Proof of address (home country)
  4. Initial deposit (varies by bank, typically AED 3,000-5,000)
  5. Some banks offer remote account opening for property buyers

Alternatives

  • International bank with UAE operations (HSBC, Standard Chartered)
  • Manager's cheque from overseas bank (for cash purchases)

Purchase Steps

  1. Market Research & Strategy

    Duration
    2-4 weeks
    Cost
    Minimal (agent consultation typically free)

    Research the UAE property market, understand freehold zones, and define your investment strategy. Engage a RERA-licensed real estate agent early in the process.

    Requirements

    • Define investment objectives (capital appreciation, rental yield, or personal use)
    • Research freehold areas and price points per sq ft
    • Understand the difference between Dubai, Abu Dhabi, and Sharjah markets
    • Budget planning: purchase price + 7-8% transaction costs (4% DLD + 2% agent + fees)
    • Engage a RERA-licensed real estate agent

    Tips

    • Focus on established freehold areas with strong rental demand (Dubai Marina, JVC, Business Bay)
    • Consider proximity to metro stations -- this significantly impacts rental demand and values
    • Research developer track records using RERA's developer database
    • For Golden Visa purposes, ensure the property meets the AED 2M minimum threshold
  2. Property Selection & Due Diligence

    Duration
    2-8 weeks
    Cost
    AED 500-2,000 (property inspection if applicable)

    Identify suitable properties through your agent, conduct viewings or review off-plan project details, and perform due diligence on the developer and property.

    Requirements

    • View properties or off-plan show apartments
    • Verify property is in a designated freehold area
    • Check developer credentials and RERA registration (for off-plan)
    • Verify title deed status via Dubai Land Department (for resale)
    • Review service charge history and community rules

    Tips

    • For off-plan: verify the developer's escrow account with RERA
    • For resale: request the latest service charge statement and check for outstanding fees
    • Compare price per square foot against recent transactions in the same building/area
  3. Legal Process & Contract

    Duration
    2-4 weeks
    Cost
    10% deposit (Form F/MOU stage) + legal fees (AED 5,000-15,000)

    Once you've selected a property, the legal purchase process begins. For resale, this involves signing a Memorandum of Understanding (Form F) and paying a deposit. For off-plan, you'll sign a Sales and Purchase Agreement (SPA) directly with the developer.

    Requirements

    • Valid passport (minimum 6 months validity)
    • Sign MOU (Form F) for resale or SPA for off-plan
    • Pay 10% deposit to escrow (resale) or developer (off-plan)
    • Obtain No Objection Certificate (NOC) from the developer (resale only)
    • Open a UAE bank account (required for mortgage and utility payments)
    • Arrange financing: mortgage pre-approval or proof of funds

    Tips

    • NOC fees are paid by the seller but can be a point of negotiation
    • For mortgage purchases, get pre-approval before signing the MOU
    • Consider appointing a property lawyer for contract review, especially for high-value transactions
    • Power of Attorney can be arranged for remote buyers who cannot attend in person
  4. Registration & Title Transfer

    Duration
    1-2 weeks
    Cost
    4% DLD registration fee + AED 580 admin fee + AED 4,200 title deed fee

    The final step is registering the property with the Dubai Land Department (DLD) or equivalent authority. Both buyer and seller (or their representatives) attend the DLD trustee office to complete the transfer.

    Requirements

    • Pay remaining balance or confirm mortgage disbursement
    • Pay 4% DLD registration fee (typically split 50/50 buyer/seller, but negotiable)
    • Both parties attend DLD trustee office (or via Power of Attorney)
    • Receive title deed in buyer's name
    • Transfer utility accounts (DEWA for Dubai, ADDC for Abu Dhabi)

    Tips

    • The DLD registration fee of 4% is the largest single transaction cost -- ensure it is budgeted
    • Title deed is issued same-day at the trustee office upon completion
    • For Abu Dhabi purchases, registration is through the Abu Dhabi Department of Municipalities and Transport
    • Keep all transaction documents for visa applications and future resale

Property Types

Completed (Ready) Properties

Ready-to-occupy properties in established communities. These are the most straightforward investment option, offering immediate income potential and clear valuation. Popular areas include Dubai Marina, Downtown Dubai, JBR, and Abu Dhabi's Saadiyat Island.

Advantages

  • Immediate rental income generation
  • No construction or completion risk
  • Can be physically inspected before purchase
  • Eligible for Golden Visa (AED 2M+ threshold)
  • Mortgage financing available from UAE banks

Disadvantages

  • Higher entry price compared to off-plan
  • Older properties may have higher service charges
  • Less flexibility on payment terms (typically requires full payment or mortgage)
  • Renovation may be needed for older stock
Typical timeline
4-6 weeks from MOU signing to DLD title deed transfer
Financing options
UAE bank mortgages (50-75% LTV), Cash purchase, International bank financing

Off-Plan Properties

Properties purchased during construction or pre-launch phase. The UAE off-plan market is highly regulated by RERA, which requires developers to register escrow accounts and meet financial requirements before selling. Common payment structures are 60% during construction / 40% on handover, though plans vary by developer.

Advantages

  • Lower entry prices (typically 10-30% below completed market value)
  • Flexible developer payment plans (60/40, 70/30, or post-handover plans)
  • Potential capital appreciation during construction period
  • Brand new property with modern specifications and warranty
  • RERA escrow protection for buyer deposits

Disadvantages

  • Construction delay risk (though RERA-regulated)
  • No immediate rental income during construction (typically 2-4 years)
  • Developer solvency risk (verify RERA registration and escrow account)
  • Final product may differ from marketing materials
  • Market conditions may change during construction period
Typical timeline
2-4 years from booking to handover (varies by project stage)
Financing options
Developer payment plans (most common), Bank pre-approval for handover payment, Cash installments

Secondary Market (Resale) Properties

Resale properties in the secondary market. These offer the advantage of established rental histories and community track records. Prices may be more negotiable than developer sales, and the buyer can benefit from existing tenancy agreements.

Advantages

  • Proven rental track record and tenant history
  • Established community with known service charge levels
  • Negotiable pricing (especially motivated sellers)
  • Immediate occupancy or rental income potential

Disadvantages

  • May require renovation or maintenance investment
  • Older buildings may have higher service charges
  • Less modern specifications compared to new developments
  • Transfer fees and agent commissions apply
Typical timeline
4-8 weeks from agreement to title transfer (NOC process adds time)
Financing options
UAE bank mortgages, Cash purchase, International bank financing

Investment Drivers

Tax-Free Investment Environment

PositiveLong termHigh confidence

The UAE offers a completely tax-free environment for property investors -- no personal income tax, no capital gains tax, and no annual property tax. This structure is constitutionally embedded and has been consistent since the federation was established, making it one of the most attractive tax regimes globally for real estate investment.

Dubai 2040 & Abu Dhabi 2030 Master Plans

PositiveLong termHigh confidence

The Dubai 2040 Urban Master Plan is reshaping the emirate with expanded green spaces, new residential communities, and enhanced infrastructure connecting key growth corridors. Abu Dhabi Economic Vision 2030 similarly targets economic diversification. These long-term government plans provide visibility on future development and infrastructure investment.

Economic Diversification & Tourism Growth

PositiveLong termHigh confidence

The UAE has successfully diversified beyond oil, with non-oil sectors now contributing over 70% of GDP. Tourism targets of 25 million visitors annually (Dubai), the ADGM and DIFC financial hubs, and a growing technology ecosystem (including AI strategy leadership) create sustained economic momentum and property demand.

Golden Visa & Residency Programs

PositiveLong termHigh confidence

The Golden Visa program (10-year residency for AED 2M+ property investment) has been a major demand driver, attracting long-term investor commitment. Expanded categories now include entrepreneurs, specialized talent, and retirees, broadening the pool of potential property buyers and residents.

AED-USD Currency Peg Stability

PositiveLong termHigh confidence

The AED is pegged to the US Dollar at a fixed rate of AED 3.6725 per USD, eliminating currency risk for dollar-denominated investors and providing stability for all international buyers. This peg has been maintained since 1997 and is backed by substantial foreign reserves.

World-Class Lifestyle & Safety

PositiveLong termHigh confidence

The UAE consistently ranks among the safest countries globally, with world-class healthcare, education, and infrastructure. The combination of zero income tax, modern amenities, year-round sunshine, and a cosmopolitan lifestyle attracts high-net-worth individuals, creating sustained premium property demand.

Visa & Residency

The UAE offers some of the most attractive residency-by-investment programs globally, directly linked to property ownership. The Golden Visa program, significantly expanded since 2022, grants long-term residency (5 or 10 years) to property investors meeting minimum thresholds. Property ownership can also qualify investors for shorter-term residence visas, making the UAE one of the few countries where real estate purchase provides a clear path to legal residency.

Golden Visa (10-Year) -- Property Investment

The flagship residency program for property investors. Grants 10-year renewable residency for property investments of AED 2 million or more. The property must be completed (not off-plan) and not subject to a mortgage exceeding 50% of its value at the time of application. Multiple properties can be combined to meet the threshold.

Minimum investment
AED 2,000,000 (~USD 545,000)
Duration
10 years, renewable
Processing time
2-4 weeks (after document submission)

Benefits

  • Long-term residency for investor, spouse, and children (no age limit for unmarried daughters)
  • No sponsor required -- self-sponsored visa
  • Ability to sponsor domestic workers
  • Multiple entry and exit with no minimum stay requirements
  • Automatically renewable upon maintaining the property investment
  • Access to UAE banking, healthcare, and education systems

Requirements

  • Property value of AED 2M or more (completed, not off-plan)
  • Title deed in applicant's name
  • Property not mortgaged for more than 50% of value
  • Valid passport with minimum 6 months validity
  • Health insurance valid in the UAE
  • Clean criminal record
  • Multiple properties can be combined to meet the AED 2M threshold

Property Investor Visa (2-Year)

A shorter-term residency visa tied to property ownership. Historically available for properties valued at AED 750,000 or more, though thresholds are periodically updated. This visa category is suitable for investors below the Golden Visa threshold who still want UAE residency.

Minimum investment
AED 750,000 (~USD 204,000)
Duration
2-3 years, renewable
Processing time
2-3 weeks

Benefits

  • Residency for investor and immediate family
  • No sponsor required
  • Multiple entry and exit privileges
  • Lower investment threshold than Golden Visa
  • Renewable upon maintaining investment

Requirements

  • Property value meeting the minimum threshold
  • Title deed in applicant's name
  • Valid passport
  • Health insurance valid in the UAE
  • Proof of income or financial self-sufficiency

Retirement Visa (5-Year)

Available for retirees aged 55+ with property investment, financial savings, or income meeting specified thresholds. This can be combined with property ownership as one of the qualifying criteria.

Minimum investment
AED 1,000,000 in property (or equivalent financial savings/income)
Duration
5 years, renewable
Processing time
2-4 weeks

Benefits

  • Long-term residency through retirement
  • Access to UAE healthcare and lifestyle
  • Can be combined with property investment
  • No employment required

Requirements

  • Age 55 or older
  • Property worth AED 1M+, OR savings of AED 1M+, OR monthly income of AED 20,000+
  • Health insurance valid in the UAE
  • Valid passport
  • No criminal record

Visa and residency regulations in the UAE change frequently and vary by emirate. The thresholds and requirements listed above reflect the latest publicly available information as of early 2026. Always consult a licensed UAE immigration advisor or PRO (Public Relations Officer) service for current requirements before making investment decisions based on visa eligibility.

Financing

The UAE has a well-developed mortgage market with multiple financing options for foreign buyers. Both conventional and Islamic financing are widely available. Non-residents can access mortgage financing from major UAE banks including ADCB, Emirates NBD, Mashreq Bank, and HSBC Middle East. Developer payment plans offer an alternative route, particularly for off-plan purchases, often requiring no mortgage at all.

Mortgage availability

Open to foreign buyers

Non-resident foreign buyers can obtain mortgages from UAE banks, though with stricter terms than residents. Most major banks have dedicated international buyer desks. LTV ratios are lower for non-residents (typically 50% for properties over AED 5M), and minimum property values usually apply (AED 500K-1M depending on the bank). Pre-approval can be obtained before property selection.

Typical LTV
50-75% (residents up to 80% for first property under AED 5M; non-residents typically 50-60%)
Interest rates
4.5-7.0% (2025; variable rates from ~4.5%, fixed rates from ~5.5% for 1-5 year terms)
Term length
Up to 25 years (property must not exceed 20 years of age at loan maturity)

Requirements

  • Valid passport with minimum 6 months validity
  • Proof of income (salary certificates or audited accounts for self-employed)
  • Bank statements (typically 6 months)
  • Existing liability declarations
  • Property valuation report (arranged by the bank)
  • Minimum salary requirements vary by bank (typically AED 15,000-25,000/month or equivalent)

Alternative financing

Developer Payment PlansCommon for off-plan and new launches; most major developers offer plans
Many UAE developers offer attractive payment plans for off-plan purchases, typically structured as 60/40 or 70/30 (construction/post-handover). Some developers offer extended post-handover plans of 3-5 years, making entry more accessible without traditional mortgage financing.
Islamic Finance (Ijara / Murabaha)Available through UAE-based Islamic banks (Dubai Islamic Bank, Abu Dhabi Islamic Bank)
Sharia-compliant financing through Ijara (lease-to-own) or Murabaha (cost-plus) structures. Terms and LTV ratios are generally comparable to conventional mortgages, though the fee structure differs.
Interest-Free InstallmentsOffered by select developers for premium projects
Some developers provide interest-free installment plans during the construction period, with milestone-based payments tied to construction progress (e.g., 10% on booking, 10% on foundation, etc.).

Mortgage terms, interest rates, and eligibility criteria change frequently and vary by lender. Consult a licensed UAE mortgage broker or financial advisor for current options tailored to your situation.

Figures are indicative and subject to change. Regulations, taxes and market conditions vary by jurisdiction. Do your own due diligence and seek independent legal and financial advice.

Keep reading

All country guides